

Top Tech Companies in Singapore (3,736)

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Record quarterly revenue and raised outlooks indicate accelerating top-line momentum across recent quarters. Growth is concentrated in Networking and Cloud & AI, contributing to substantial year-over-year gains.
Profitability: Operating profit and margins expanded significantly with record operating results reported. This improvement accompanies heightened demand in AI infrastructure, servers, and networking.
Healthy Cash Flow: Operating cash flow and free cash flow increased versus the prior year, reflecting stronger cash generation alongside growth. Management also pointed to higher full-year free cash flow expectations.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.
Tulip, the leader in frontline operations, is helping companies around the world equip their workforce with connected apps, leading to higher quality work, improved efficiency, and end-to-end traceability across operations. Companies of all sizes and across industries have implemented composable solutions with Tulip’s cloud-native, no-code platform to solve some of the most pressing challenges in operations: error-proofing processes and boosting...
Tulip's Top Stability & Growth Strengths
Strong Revenue Growth: Tulip reported 536% revenue growth over three years and cited its 2024 Deloitte Technology Fast 500 ranking as evidence of rapid top-line expansion. This momentum is further supported by disclosures of large increases in customer deployments and usage through 2025.
Investor Backing & Capital Strength: A $120M Series D announced in January 2026 at a stated $1.3B valuation, led by Mitsubishi Electric, is presented as funding further growth and expansion. Strategic investment alongside a commercial alliance signals durable capital access and support.
Market Expansion: Headcount reportedly grew 135% to 300+ with new offices opened in Singapore, Munich, Budapest, Tokyo, and Tel Aviv. The company also points to scale across 1,000 customer sites in 45 countries as of 2025.
.png)
Crypto creates economic freedom by ensuring that people can participate fairly in the economy, and Coinbase (NASDAQ: COIN) is on a mission to increase economic freedom for more than 1 billion people. We’re updating the century-old financial system by providing a trusted platform that makes it easy for people and institutions to engage with crypto assets, including trading, staking, safekeeping,...
Coinbase's Top Stability & Growth Strengths
Diversified Revenue Streams: Subscription & services revenue reached $555 million in Q2 2026 and accounted for 48% of net revenue, reflecting growth in stablecoins, staking, interest/finance income, and other services. This indicates reduced reliance on transaction fees as the mix shifts toward recurring and non-trading lines.
Strong Market Position & Advantage: Crypto trading-volume market share rose to 10.3% in Q2 2026, up from 9.1% in Q1, marking a third consecutive quarter of share gains. This points to competitive momentum even as overall market activity softened.
Product Line Growth: New offerings scaled rapidly, with prediction-market contracts and revenue up 106% quarter over quarter in Q2 2026. Average USDC held in Coinbase products also hit an all-time high of $20 billion, underscoring product traction.
Adyen (ADYEN:AMS) is the financial technology platform of choice for leading companies. By providing end-to-end payments capabilities, data-driven insights, and financial products in a single global solution, Adyen helps businesses achieve their ambitions faster. With offices around the world, Adyen works with the likes of Meta, Uber, H&M, eBay, and Microsoft.
Adyen's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a sustained double‑digit pace across multiple periods, and management increased its constant‑currency growth outlook for 2026 after a strong first half. The company is also described as growing faster than the broader payments market by deepening share of wallet with major global merchants.
Profitability: Operating performance remains robust, with EBITDA expanding faster than revenue in 2025 and margins staying very high into 2026. This points to meaningful operating leverage alongside continued scale.
Product Line Growth: Expansion beyond core online payments is evident, with Unified Commerce and Platforms showing rapid gains and newer areas such as issuing, intelligent money movement, and agentic payments ramping. Recent acquisitions (e.g., loyalty and usage‑based billing) further broaden capabilities and potential revenue streams.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Profitability: The company is described as privately held, profitable, and debt-free, indicating a solid financial base. This positioning supports continued investment without reliance on external financing.
Strong Revenue Growth: Revenue is reported above $1 billion with indications of year-over-year increases into 2024 and sustained scale into FY2025, while cloud segments are noted as expanding strongly. These signals point to ongoing top-line momentum.
Market Expansion: Operations span 28 countries with 38 offices serving customers in 80+ countries, alongside recent moves such as a dedicated public-sector subsidiary and added international presence. This footprint suggests continued geographic and channel growth.
At monday.com, we help teams get more work done. We are the best AI work platform that empowers teams to automate, build, and scale their impact end-to-end with tools that actually execute the work for you. With over $1B in ARR, 250,000+ customers, and a global team, we’re serious about building a product people love to use and giving our...

monday.com's Top Stability & Growth Strengths
Profitability: Net income reached $118.7 million in 2025 versus $32.4 million in 2024 and a small loss in 2023, alongside record non‑GAAP operating income and margin improvements in 2026. This indicates the company is scaling efficiency while expanding.
Strong Revenue Growth: Revenue rose 27% in 2025 to $1.232 billion and continued to increase 22% year over year in Q2 2026, with management guiding 19%–20% growth for 2026. While the pace has moderated from earlier years, the top line remains firmly upward.
Innovation-Driven Growth: ARR from AI products doubled quarter over quarter in Q2 2026 and represented 17% of net new ARR. The pivot to an AI work platform is contributing discernible incremental demand.
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Consolidated revenue has increased across recent years, with additional year-over-year gains extending into early 2026. This pattern indicates ongoing top-line expansion even as quarterly and annual growth rates vary.
Profitability: Operating income reached new highs in 2025 and continued to rise in subsequent quarters. This points to improving operating leverage alongside revenue growth.
Product Line Growth: Businesses such as Morningstar Credit, PitchBook, Retirement, and the Direct Platform are cited as key growth engines, with Credit standing out. This breadth of product contributions supports expansion beyond a single offering.
Apryse, previously known as PDFTron, takes document solutions to the next level, making work better and life simpler. As a global leader in document processing technology, Apryse gives developers, enterprise customers, and small businesses the tools they need to reach their document goals faster and easier. Apryse’s market-leading SDK drives digital transformation and powers next-generation software applications with dynamic document...
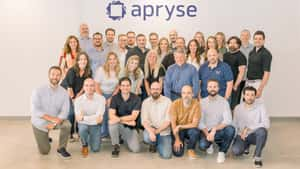
Apryse's Top Stability & Growth Strengths
Strong Revenue Growth: Reuters reporting indicates annual growth at a strong double-digit pace in 2025, aligning with sustained expansion activity. This growth is presented alongside ongoing platform and market advances from 2024–2026.
Profitability: EBITDA reportedly exceeded $100 million, indicating robust earnings capacity. This profile underpinned exploration of a multibillion-dollar sale process in 2025.
Product Line Growth: Acquisitions across 2024–2026 (e.g., LEAD Technologies, TallComponents, Scanbot SDK, Accusoft, PDF Tools AG) materially expanded capabilities in imaging, mobile capture, and high-performance PDF processing. Regular release cadences and AI-driven features further signal continued product expansion.


Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins expanded, with Q2 2026 EBITDA up 30% year over year and margin improving to 37%, alongside higher net income. This pattern indicates operating leverage as earnings outpace the top line.
Strong Revenue Growth: Revenue rose 7% in 2025 and accelerated to 11% year over year in Q2 2026, with multiple sequential quarters showing improving trends. The recent trajectory points to faster growth rather than a flat profile.
Healthy Cash Flow: Free cash flow is guided to grow at more than 30% for 2026 and was later raised to the high-40% range, while Q2 2026 generated $57.4M in operating cash. Debt reduction in 1H 2026, including repayment of $205M in convertibles, further supports balance-sheet strength.
CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue are increasing at a robust pace, with recent quarters showing re-acceleration and a raised full‑year outlook. This momentum is supported by record net new recurring business and continued customer and module expansion.
Healthy Cash Flow: Operating and free cash flow are at record levels for recent periods, underscoring strong cash generation alongside growth. Liquidity is reinforced by scaling cash from operations as the platform expands.
Profitability: GAAP profitability has improved from prior losses to positive territory, with operating leverage trending upward. This shift indicates improving economics as scale increases.
Airwallex is the only unified payments and financial platform for global businesses. Powered by our unique combination of proprietary infrastructure and software, we empower over 250,000+ businesses worldwide – including Brex, Navan, Qantas, SHEIN, McLaren and many more – with fully integrated solutions to manage everything from business accounts, payments, spend management and treasury, to embedded finance at a global...
Airwallex's Top Stability & Growth Strengths
Strong Revenue Growth: Annualized revenue increased from $720M in March 2025 to $1.3B by March 2026, with ARR surpassing $1B in late 2025 and continuing upward. This trajectory points to sustained top-line momentum across the period cited.
Market Expansion: Geographic reach broadened with new regulated entries across multiple regions, alongside plans to deploy over $1B in the U.S. and substantial investment in Europe. Regional performance in the Americas and EMEA also advanced meaningfully, indicating traction beyond APAC.
Investor Backing & Capital Strength: Valuation rose from $6.2B (May 2025) to $11B (June 2026) through successive large funding rounds. Independent reporting corroborated the latest financing, signaling strong capital access and external confidence.
Hilton (NYSE: HLT) is a leading global hospitality company with a portfolio of 28 world-class brands comprising more than 9,400 properties and nearly 1.4 million rooms, in 144 countries and territories. Dedicated to fulfilling its founding vision to fill the earth with the light and warmth of hospitality, Hilton has welcomed over 4 billion guests in its more than 100-year...

Hilton's Top Stability & Growth Strengths
Market Expansion: Hotel footprint is widening, with properties and rooms increasing, approvals for additional rooms, and a record development pipeline by mid-2026. The network spans over 140 countries and reflects continued entry into new markets.
Strong Revenue Growth: Revenue rose to about $12.04B in 2025 from the prior year, and early 2026 showed gains in system-wide comparable RevPAR. Management also indicated continued comparable RevPAR growth for 2026.
Product Line Growth: The portfolio is expanding with new brands and lodging categories, including the Apartment Collection and the conversion-focused Outset Collection. Broader offerings in lifestyle and luxury support conversions and attract a wider range of owners and travelers.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.
Sonar provides the essential verification layer for the AI-driven development era, ensuring all code—whether human-written or AI-generated—is code you can trust. Today, AI coding tools are generating explosive volumes of code. This has created an "engineering productivity paradox" : faster code writing doesn't automatically lead to faster, safer software delivery. The new bottleneck is verification. Sonar solves this. Integrating code quality and...

Sonar's Top Stability & Growth Strengths
Strong Revenue Growth: ARR has surpassed $430 million with accelerated growth, and expectations of 22–23% revenue increases in 2026–27 reinforce ongoing momentum. This scale is bolstered by tens of thousands of paying customers and broad enterprise adoption, including a large share of Fortune 100 companies.
Innovation-Driven Growth: New AI-centric offerings (e.g., Sonar Vortex and a SonarQube Remediation Agent) and the 2026 acquisition of Gitar extend the platform into AI-native code verification and review. This product cadence signals active investment to capture emerging developer and DevSecOps use cases.
Investor Backing & Capital Strength: A $412 million financing at a $4.7 billion valuation led by Advent International and General Catalyst, with Insight Partners and Permira, provides resources to scale globally. Stated plans to pursue $1 billion in revenue underline sustained access to growth capital.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
Flywire is a global payments enablement and software company. We combine our proprietary global payments network, next-gen payments platform and vertical-specific software to deliver the most important and complex payments for our clients and their customers.
Flywire's Top Stability & Growth Strengths
Strong Revenue Growth: Recent filings and earnings updates indicate sustained double-digit increases across annual and quarterly revenue, with momentum continuing into 2026. Guidance was raised during the year, reinforcing ongoing top-line expansion across core verticals.
Profitability: Results point to improving earnings quality, including a shift to positive net income on an annual basis and expanding adjusted EBITDA margins. Management also signaled further margin gains in 2026.
Customer Loyalty & Retention: Disclosures highlight a growing client base alongside net dollar-based retention that indicates expansion within existing customers. Wins across education, travel, healthcare, and B2B suggest durable relationships that support recurring growth.
CWAN was founded on a simple belief: investment professionals deserve modern technology that actually works for them. Not legacy systems that slow them down. Not fragmented data that creates confusion. But one comprehensive platform that gives you complete visibility and crystal-clear insights. The result? Investment management that works as seamlessly as your investment strategy. Since our founding in 2004, CWAN has been...

Clearwater Analytics (CWAN)'s Top Stability & Growth Strengths
Strong Revenue Growth: Total revenue increased substantially from 2024 to 2025 and continued to rise sharply into Q1 2026, including $731.4 million in 2025 and $221.2 million in Q1 2026. ARR also climbed to $872 million by Q1 2026, reinforcing momentum in the recurring model.
Customer Loyalty & Retention: Gross revenue retention remained very high and net revenue retention stayed above 100%, indicating expansion within the existing customer base. These metrics suggest growth is not solely reliant on adding new customers.
Profitability: Adjusted EBITDA grew strongly with healthy margins and non-GAAP net income increased alongside scale. Results in late 2025 and Q1 2026 highlighted rising adjusted earnings during rapid expansion.

IDeaS is a company of innovators, collaborators, and educators. Founded in 1989, with the goal to revolutionize revenue management for businesses worldwide. The company's founders were pioneers in revenue science, and IDeaS has continued to lead the way in this field ever since, particularly in the hospitality and travel industries. We use advanced mathematics and industry expertise to turn data into...
IDeaS's Top Stability & Growth Strengths
Strong Revenue Growth: Regional revenue is reported to have surged, including a 426% year-over-year increase in Greece from 2023 to 2024 and a doubling in the DACH region in 2024. These results indicate accelerating commercial momentum in multiple markets.
Market Expansion: Customer footprint is described as rising from 30,000+ properties in 2023 to 34,000+ across more than 160 countries, alongside new agreements with hotel groups and cruise operators. This points to continued international penetration and widening presence across segments.
Product Line Growth: Offerings have expanded beyond core hotel RMS into meetings/events, budgeting, marketing optimization, parking, and cruise, with new products such as Spotlight and Rate Data Advantage seeing rapid uptake (e.g., 1,600+ adoptions within 100 days). This breadth supports additional use cases and cross-sell potential.



