

Top IT Companies in Singapore (674)
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in 2025 and accelerated further in early 2026, with adjusted operating income also rising. This points to broad-based top-line momentum beyond a single period.
Strong Market Position & Advantage: The company is characterized as the world’s largest asset manager with record-high assets under management and leading ETF scale. This scale advantage underpins continued client inflows and platform reach.
Diversified Revenue Streams: Growth is coming from multiple engines, including iShares ETFs, active strategies, private markets, and technology services such as Aladdin, alongside newer digital-asset offerings. This breadth reduces reliance on any single product line.
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show operating revenue rising at double‑digit rates across FY2025 and FY2026, with annualized recurring revenue increasing even faster. Growth is supported by both subscriber additions and higher average revenue per customer.
Healthy Cash Flow: Free cash flow increased year over year, indicating stronger cash generation alongside expansion. Reported figures highlight rising cash metrics even as the company scales investments.
Market Expansion: International revenue and subscribers continued to grow, with substantial gains outside Australia/New Zealand and ongoing progress in the U.S. aided by product and acquisition initiatives. Regional momentum in markets like the UK and North America underscores a widening footprint.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising year over year in 2025 and accelerating to double‑digit growth in early 2026, with management raising its full‑year outlook. Bookings and room nights are also increasing, reinforcing the top‑line trend.
Profitability: Profitability expanded faster than revenue in 2025 and continued to improve in 2026, including margin expansion in the latest quarter. This indicates operating leverage and stronger earnings quality alongside growth.
Diversified Revenue Streams: B2B has been growing much faster than the consumer business, and advertising/media also expanded strongly in 2025. Multiple engines—B2B, lodging, and advertising—are contributing materially to overall expansion.

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Record quarterly revenue and raised outlooks indicate accelerating top-line momentum across recent quarters. Growth is concentrated in Networking and Cloud & AI, contributing to substantial year-over-year gains.
Profitability: Operating profit and margins expanded significantly with record operating results reported. This improvement accompanies heightened demand in AI infrastructure, servers, and networking.
Healthy Cash Flow: Operating cash flow and free cash flow increased versus the prior year, reflecting stronger cash generation alongside growth. Management also pointed to higher full-year free cash flow expectations.
Skillsoft (NYSE: SKIL) is a global leader in AI-native skills management for the human + AI era. By unifying learning, real-time skills intelligence, and workforce insights, Skillsoft helps enterprises build their Skillforce™ — humans and AI working together to drive measurable business outcomes. Through personalized, interactive learning across leadership, technology, and compliance, Skillsoft enables organizations to close critical skill gaps...

Skillsoft's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted EBITDA held roughly stable to slightly higher year over year and free cash flow improved in the latest periods, indicating tighter operations despite softer sales. Management focus on efficiency helped margins while the business pivots toward subscriptions and AI.
Innovation-Driven Growth: A next‑generation AI‑native Percipio platform is in market with new customers, and usage of AI capabilities (including CAISY and related tools) is rising among early adopters. These signals point to product‑led momentum within the core enterprise offering even as consolidated revenue declines.
Customer Loyalty & Retention: Enterprise subscription revenue has been comparatively resilient across recent years, with indicators like improved dollar retention and steady TDS performance suggesting stable customer relationships. Professional‑services revenue also increased, reinforcing ongoing engagement with enterprise accounts.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.
.png)
In March of 2002, Belvedere Trading emerged as Chicago’s newest market maker, soon to join the ranks of the Windy City’s elite proprietary trading firms. Armed with printouts of Excel workbooks and a team of eager minds, Belvedere established their place in the SPX pit on the floor of the Chicago Board Options Exchange. From the beginning, we have iteratively...
Belvedere Trading's Top Stability & Growth Strengths
Product Line Growth: Company updates point to a meaningful increase in product count in 2024, expanding the breadth of tradable products. Available evidence suggests this reflects operating-scale growth beyond hiring alone.
Market Expansion: The firm operates across Chicago, Boulder, New York, and Singapore, and signals expansion into new instruments and marketplaces domestically and globally. Physical office build-outs in Chicago further indicate an expanded footprint to accommodate growth.
Innovation-Driven Growth: Reported large increases in computing resources and major network upgrades in 2024 underscore ongoing investment in proprietary technology and infrastructure. Available evidence suggests these capacity gains are aimed at scaling trading capabilities.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue and ARR continued to rise, with ARR surpassing $300M by 2025 and revenue increasing in 2024. Feedback suggests growth has moderated from earlier hypergrowth into a steadier, efficiency‑focused trajectory while the customer base expanded to 4,500+.
Product Line Growth: Snyk Code reached $100M in ARR and newer offerings such as DAST and AI‑focused products (e.g., Evo) showed strong momentum. These developments indicate the platform is extending beyond its original core into additional security categories.
Market Expansion: Enterprise adoption intensified, with that segment driving a large share of new additions and AI security opening fresh routes to demand. Customer counts grew materially from 2024 into 2025, signaling broader market reach.

At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Bottom-line performance is strengthening, with consistent earnings beats, improved non-GAAP operating income, and durable free cash flow. Management is prioritizing margin expansion alongside operational efficiency.
Healthy Cash Flow: The business is generating solid free cash flow, with recent periods and guidance pointing to sustained cash generation. This supports stability even as revenue growth moderates.
Strong Market Position & Advantage: The company is repeatedly recognized as a leader in MDR, exposure management, and SIEM by major analyst programs. A large global customer base underscores established scale in its core markets.
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 2025 trading revenue rose to $12.2B from $9.7B in 2024, and 2026 featured record quarters such as a $7.3B Q2, indicating material topline expansion. EBITDA was also reported higher in 2025, reinforcing financial momentum.
Strong Market Position & Advantage: The company indicates it executes a substantial portion of daily U.S. equity and retail trading volumes and holds a top rank on Tradeweb for U.S. Treasury flows, underscoring entrenched scale. Leadership in listed options and as an NYSE Designated Market Maker further points to durable competitive advantage.
Market Expansion: New initiatives such as launching a High Touch Equities business in late 2025, opening an Amsterdam office in 2026, and operating across 50+ equity and fixed‑income markets signal active expansion. Ongoing hiring—1,800+ employees, dozens of open roles across regions, and the firm’s largest intern class—suggests continued investment in capacity.

Bounteous is a global AI Services firm where agentic engineering and human experience converge to deliver transformative business outcomes for the enterprise. We help organizations design, build, and scale AI-driven products, platforms, and processes. With more than 5,000 team members worldwide, Bounteous delivers AI that sticks, powering adoption and outcomes that move organizations from experimentation to true transformation.

Bounteous's Top Stability & Growth Strengths
Market Expansion: The company has scaled through the 2024 Accolite merger and the 2026 Cartesian acquisition, which broaden capabilities and extend its North American and European footprint. Hiring initiatives in India and emphasis on EMEA growth further indicate a wider geographic reach.
Innovation-Driven Growth: The organization has repositioned from digital transformation toward AI services, with recent moves explicitly adding data, analytics, and enterprise AI capabilities. This shift aligns offerings with higher-growth categories.
Diversified Customer Base: Following the Accolite combination, the firm cites serving hundreds of Fortune 1000 and high-growth clients. This signals access to a broad enterprise demand base.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
Coupa is a global technology company that helps businesses run smarter by connecting all the ways they spend money — from procurement and expenses to payments and supply chain decisions — in one intelligent platform. In simple terms, Coupa gives organizations the visibility and control they need to make better financial choices, reduce waste, and drive real impact. It’s where...
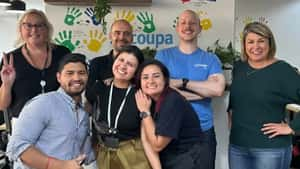
Coupa's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as reaching a record level in Q4 FY2026, with continued ARR growth and earlier double‑digit bookings gains indicating ongoing top‑line momentum.
Customer Loyalty & Retention: Renewals and expansions are emphasized, with more than 1,300 organizations renewing or expanding in FY2026. This points to durable engagement within the installed base.
Innovation-Driven Growth: Product advances such as AI agents and new applications, alongside acquisitions like Rossum and Tonkean, are expanding the platform’s capabilities. These moves are linked to increased adoption and expansion activity.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR moved from surpassing $300M in June 2025 to exceeding $400M by May 2026, indicating a substantial year-over-year increase. The company also reported a 36% five-year organic CAGR in 2024, underscoring sustained momentum.
Product Line Growth: Edwin AI recurring revenue is reported to be growing around 200% year over year and contributing about one-third of total bookings. The December 2025 Catchpoint acquisition expanded capabilities into internet performance and digital experience monitoring.
Market Expansion: Larger enterprise accounts grew more than 25% year over year in 2025 and the company cited 700+ enterprise customers by late 2025. More than 30% of new customers came from outside the U.S., indicating ongoing international expansion.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is scaling at strong double-digit rates, reaching $702M in FY2026 and continuing to rise in subsequent quarters, with full‑year FY2027 guidance lifted into the low‑$900M range. Multiple updates indicate momentum in both reported results and outlook.
Healthy Cash Flow: Operating cash flow turned positive in FY2026 and free cash flow was also positive, alongside progress in non‑GAAP profitability in later quarters. These milestones suggest improving financial efficiency as scale increases.
Diversified Customer Base: The company reports 12,500+ active customers and continued wins with large enterprises across technology, manufacturing, and healthcare. This breadth points to demand resilience across multiple industries.
Welcome to Comcast. From the connectivity and platforms we provide to the content and experiences we create, we bring people together, globally. Our people think the world of our work, and that’s why our work is the best in the world.

Comcast's Top Stability & Growth Strengths
Healthy Cash Flow: Operating cash flow increased from $27.7 billion in 2024 to $33.6 billion in 2025, and Q2 2026 free cash flow was $4.6 billion, up 2.3% year over year. This indicates strong cash generation despite uneven top-line trends.
Diversified Revenue Streams: Connectivity revenue rose 4.2% to $46.0 billion in 2025 alongside growth in business services (to $10.2 billion), wireless lines (to 9.3 million), Peacock (revenue up 10% to $5.4 billion; paid subs up 22% to 44 million), and parks. Comcast also highlights six growth drivers—broadband, wireless, business services, studios, streaming, and parks—that represented about 60% of 2025 revenue.
Product Line Growth: Wireless and streaming scaled meaningfully, with approximately 1.5 million wireless line additions in 2025 and Peacock reaching 44 million paid subscribers that year and achieving first-time quarterly profitability in Q2 2026. Business services connectivity also expanded in 2026, including Q2 revenue up 3.7% and EBITDA up 5.0%.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.



