

Top Tech Companies in Singapore (3,716)
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 2025 trading revenue rose to $12.2B from $9.7B in 2024, and 2026 featured record quarters such as a $7.3B Q2, indicating material topline expansion. EBITDA was also reported higher in 2025, reinforcing financial momentum.
Strong Market Position & Advantage: The company indicates it executes a substantial portion of daily U.S. equity and retail trading volumes and holds a top rank on Tradeweb for U.S. Treasury flows, underscoring entrenched scale. Leadership in listed options and as an NYSE Designated Market Maker further points to durable competitive advantage.
Market Expansion: New initiatives such as launching a High Touch Equities business in late 2025, opening an Amsterdam office in 2026, and operating across 50+ equity and fixed‑income markets signal active expansion. Ongoing hiring—1,800+ employees, dozens of open roles across regions, and the firm’s largest intern class—suggests continued investment in capacity.
Ambiq® enables intelligence (AI and beyond) everywhere by delivering the lowest-power semiconductor solutions for battery-powered edge devices. As a pioneer in ultra-low power SoCs, Ambiq empowers wearables, IoT, smart home, healthcare, and industrial products with always-on, energy-efficient intelligence. Backed by our SPOT® technology and global innovation leadership, Ambiq is shaping the future of edge AI.
Ambiq 's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters show rapid acceleration, with Q1 2026 net sales rising to $25.1M and Q2 reaching $33.9M alongside five consecutive quarters of sequential growth. Guidance for Q3 2026 of $36–37M indicates the trend may continue.
Cost & Operational Efficiency: Despite FY2025 revenue declining from 2024, gross profit increased to $32.1M and gross margin expanded materially. In Q2 2026, gross profit more than doubled year over year.
Investor Backing & Capital Strength: The company completed an IPO and upsized follow-on offerings in 2026, bolstering liquidity to over $360M in cash with no debt. It also added a dual listing in Singapore to broaden its investor base.
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.
Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased solidly year over year in both the latest quarter and the full fiscal year, with momentum characterized as robust and consistent across recent periods. Company materials indicate the expansion is driven by contributions from both existing and newly added customers.
Healthy Cash Flow: Free cash flow turned positive and rose meaningfully, alongside improvements in non-GAAP operating income. These trends indicate improving cash profitability even as GAAP profitability has yet to be reached.
Customer Loyalty & Retention: Net retention indicates expansion within existing accounts, and the cohort of larger enterprise customers has grown. Together, these signals point to durable upsell and cross-sell within the installed base.
.png)
Doodle Labs designs and produces industrial-grade wireless networking solutions. The company focuses on mesh networking for robotic systems, providing high throughput, long-range Mesh Rider solutions for UAVs, UGVs, AMRs and other robotic applications. The company’s Helix Mesh Rider Radio was developed with sponsorship from DIU and is the Blue UAS program’s datalink of choice. Doodle Labs was named one of Fast...
Doodle Labs's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships are described as expanding across OEMs, integrators, and channels, including integrations with Auterion, Teledyne FLIR, Teal/Red Cat, and new agreements such as LUXUAV and distribution via Mouser. These relationships are portrayed as increasing platform embed opportunities and international reach.
Product Line Growth: The portfolio is reported to have expanded from Mesh Rider into Nano², Mini, OEM, Boost, and Wearable radios, along with Sense-EW capabilities and a mobile app. This widening set of form factors and features suggests a broader addressable market and use cases.
Market Expansion: Activity is noted across U.S. defense programs (e.g., an Army Phase II SBIR award) and into Europe through NATO-aligned pushes and the LUXUAV partnership. Company materials also highlight integrations across drones and robotics globally, indicating growing geographic and sector presence.

IDeaS is a company of innovators, collaborators, and educators. Founded in 1989, with the goal to revolutionize revenue management for businesses worldwide. The company's founders were pioneers in revenue science, and IDeaS has continued to lead the way in this field ever since, particularly in the hospitality and travel industries. We use advanced mathematics and industry expertise to turn data into...
IDeaS's Top Stability & Growth Strengths
Strong Revenue Growth: Regional revenue is reported to have surged, including a 426% year-over-year increase in Greece from 2023 to 2024 and a doubling in the DACH region in 2024. These results indicate accelerating commercial momentum in multiple markets.
Market Expansion: Customer footprint is described as rising from 30,000+ properties in 2023 to 34,000+ across more than 160 countries, alongside new agreements with hotel groups and cruise operators. This points to continued international penetration and widening presence across segments.
Product Line Growth: Offerings have expanded beyond core hotel RMS into meetings/events, budgeting, marketing optimization, parking, and cruise, with new products such as Spotlight and Rate Data Advantage seeing rapid uptake (e.g., 1,600+ adoptions within 100 days). This breadth supports additional use cases and cross-sell potential.
Wise is a global technology company, building the best way to move and manage the world's money. With Wise Account and Wise Business, people and businesses can hold 40 currencies, move money between countries and spend money abroad. Large companies and banks use Wise technology too; an entirely new network for the world's money. Launched in 2011, Wise is one...
Wise's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue increased 19% in FY2026 to about $2.5bn and rose a further 25% year over year to $714m in Q1 FY2027, indicating continued top-line momentum. Growth is broad-based alongside rising customers and cross-border volumes.
Profitability: Income before tax reached roughly $660m in FY2026, equating to a 26% margin while volumes and usage scaled. Profitability held even as the company reduced take rates to remain competitive.
Diversified Revenue Streams: Card spend grew 37% to ~$44bn and customer holdings rose ~40% to ~$39bn in FY2026, with card and other revenue also expanding, indicating monetization beyond transfer fees. Wise Platform partnerships with banks further extend revenue sources beyond direct consumer transfers.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show accelerating top-line momentum, with FY2025 up 28% and Q2 2026 revenue up 36% year over year after 32% in Q1. Management also raised 2026 revenue guidance to $4.45B–$4.47B, indicating confidence in continued expansion.
Healthy Cash Flow: Cash generation is substantial, including Q2 2026 operating cash flow of $316M and free cash flow of $279M with about a 25% free-cash-flow margin. The company also reported roughly $5.0B in cash, cash equivalents and marketable securities as of June 30, 2026.
Customer Loyalty & Retention: Expansion within the installed base is a key driver, with about 75% of the 2025 revenue increase coming from existing customers and rising multi‑product adoption. Larger accounts are also expanding, as $100K+ ARR customers grew roughly 23% year over year to ~4,720 in Q2 2026.

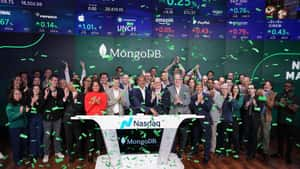
The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded at a faster year-over-year pace in the latest quarter, with multi-year increases continuing from prior fiscal years and momentum building into fiscal 2027. Recent disclosures indicate broad-based gains across subscriptions and both cloud and self-managed offerings.
Healthy Cash Flow: Operating cash flow rose sharply year over year, and free cash flow expanded alongside improving operating margins. There is also a shift to GAAP profitability, signaling stronger operating leverage.
Customer Loyalty & Retention: A high net ARR expansion rate indicates existing customers are spending more over time, complementing steady additions to the total customer base. Atlas-related consumption from larger existing accounts is cited as a key driver of subscription growth.
A global leader in applied safety science, UL Solutions transforms safety, security and sustainability challenges into opportunities for customers in more than 100 countries. UL Solutions delivers testing, inspection and certification services, together with software products and advisory offerings, that support our customers’ product innovation and business growth. The UL Certification Marks serve as a recognized symbol of trust in...
UL Solutions's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased for multiple consecutive years, surpassing $3.0B in 2025 with continued growth into early 2026, including positive organic gains across all major segments. Filings indicate the trajectory is broad-based rather than acquisition-driven.
Profitability: Profitability is expanding faster than sales, with strong adjusted EBITDA growth and notable margin improvement in 2025. Subsequent quarterly updates show further gains, reinforcing operating leverage.
Healthy Cash Flow: Operating cash flow increased to roughly $600M in 2025, with stronger free cash flow supporting continued investment in labs and capacity expansion. This cash generation underpins ongoing growth initiatives.

Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose at double‑digit rates in 2025 and continued to increase at a similar pace in early 2026, supported by higher gross dollar volume, cross‑border activity, and switched transactions. The multi‑quarter trend indicates consistent top‑line momentum rather than a one‑off spike.
Profitability: Operating income outpaced revenue growth in 2025, expanding margins, while net income and EPS also advanced strongly. This points to operating leverage as volumes and higher‑yield cross‑border flows scale.
Diversified Revenue Streams: Value‑added services and solutions grew markedly faster than the core network, with security, digital authentication, analytics, and consulting cited as key contributors. This mix shift broadens growth beyond card payment fees and supports resilience.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....
LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR moved from surpassing $300M in June 2025 to exceeding $400M by May 2026, indicating a substantial year-over-year increase. The company also reported a 36% five-year organic CAGR in 2024, underscoring sustained momentum.
Product Line Growth: Edwin AI recurring revenue is reported to be growing around 200% year over year and contributing about one-third of total bookings. The December 2025 Catchpoint acquisition expanded capabilities into internet performance and digital experience monitoring.
Market Expansion: Larger enterprise accounts grew more than 25% year over year in 2025 and the company cited 700+ enterprise customers by late 2025. More than 30% of new customers came from outside the U.S., indicating ongoing international expansion.
Adyen (ADYEN:AMS) is the financial technology platform of choice for leading companies. By providing end-to-end payments capabilities, data-driven insights, and financial products in a single global solution, Adyen helps businesses achieve their ambitions faster. With offices around the world, Adyen works with the likes of Meta, Uber, H&M, eBay, and Microsoft.
Adyen's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a sustained double‑digit pace across multiple periods, and management increased its constant‑currency growth outlook for 2026 after a strong first half. The company is also described as growing faster than the broader payments market by deepening share of wallet with major global merchants.
Profitability: Operating performance remains robust, with EBITDA expanding faster than revenue in 2025 and margins staying very high into 2026. This points to meaningful operating leverage alongside continued scale.
Product Line Growth: Expansion beyond core online payments is evident, with Unified Commerce and Platforms showing rapid gains and newer areas such as issuing, intelligent money movement, and agentic payments ramping. Recent acquisitions (e.g., loyalty and usage‑based billing) further broaden capabilities and potential revenue streams.
Sonar provides the essential verification layer for the AI-driven development era, ensuring all code—whether human-written or AI-generated—is code you can trust. Today, AI coding tools are generating explosive volumes of code. This has created an "engineering productivity paradox" : faster code writing doesn't automatically lead to faster, safer software delivery. The new bottleneck is verification. Sonar solves this. Integrating code quality and...

Sonar's Top Stability & Growth Strengths
Strong Revenue Growth: ARR has surpassed $430 million with accelerated growth, and expectations of 22–23% revenue increases in 2026–27 reinforce ongoing momentum. This scale is bolstered by tens of thousands of paying customers and broad enterprise adoption, including a large share of Fortune 100 companies.
Innovation-Driven Growth: New AI-centric offerings (e.g., Sonar Vortex and a SonarQube Remediation Agent) and the 2026 acquisition of Gitar extend the platform into AI-native code verification and review. This product cadence signals active investment to capture emerging developer and DevSecOps use cases.
Investor Backing & Capital Strength: A $412 million financing at a $4.7 billion valuation led by Advent International and General Catalyst, with Insight Partners and Permira, provides resources to scale globally. Stated plans to pursue $1 billion in revenue underline sustained access to growth capital.
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring and headcount are expanding, with disclosures of 15,000+ global employees, thousands of new hires, and third‑party estimates indicating continued workforce growth. Available evidence also points to active internal mobility and a recent increase in active job postings.
Market Expansion: Geographic and client footprints are broadening, with 40+ offices and 1,700+ customers across 170+ countries alongside concrete investments in new and expanded locations such as Hyderabad and Kingston. These moves indicate scaling delivery capacity in major capability centers and new regions.
Innovation-Driven Growth: The offering mix is shifting toward AI, data, technology, and platforms, including proprietary solutions and product capabilities. Strategic moves such as Salesforce-focused acquisitions and collaborations, plus a Tulip solution partnership, extend capabilities beyond traditional consulting.
Circle (NYSE: CRCL) is a global, internet financial platform company powering the foundation of an open, borderless, and programmable economy. Circle connects financial institutions, enterprises, and developers to the next generation of the internet financial system through digital assets such as USDC, Circle Payments Network for global money movement, and Arc, an enterprise-grade blockchain designed to become the Economic OS...

Circle's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA more than doubled to $582M in FY2025 and increased again in Q2 2026, indicating improving operating earnings. Pay is considered strengthened further by FY2025 operating earnings outpacing revenue growth.
Diversified Revenue Streams: Other revenue grew 41% in Q2 2026, while the company is expanding payments, tokenized assets, the Circle Payments Network, and its Arc blockchain. Feedback suggests this reflects progress beyond a single revenue source.
Strong Market Position & Advantage: USDC circulation and usage continued to rise (e.g., $73.3B in Q2 2026, +19% YoY; $14.8T on-chain volume, +151% YoY), alongside growth in meaningful wallets. These adoption signals reinforce standing among the largest stablecoin networks.
.png)
The Operations & Technology team at NBCUniversal powers the platforms and products behind the stories and experiences millions of people enjoy every day. Across entertainment, news, sports, theme parks, and streaming, our teams develop and support the infrastructure and production capabilities that help bring content and experiences to audiences around the world. Here, you'll solve complex challenges while shaping the future...

NBCUniversal's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show Peacock revenue up 54% year over year to $1.90 billion, Studios up 25% to about $3 billion, and NBCUniversal media and theme-park revenue up 23% to $10.7 billion in Q2 2026. Earlier in 2026, the parks business also rose 24% on the launch of Epic Universe.
Profitability: Peacock reached a key inflection with its first quarterly pre-tax profit of $189 million alongside paid subscribers rising to 48 million in Q2 2026. This points to improving streaming economics within the portfolio.
Future-Ready Strategy: Management is reshaping the portfolio by planning to spin off NBCUniversal and Sky into a standalone public company positioned to pursue growth across parks, film/TV, streaming, sports and news. The 2025 shareholder letter also highlights studios, streaming and parks as principal growth drivers representing a large share of Comcast’s revenue.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Profitability: The company is described as privately held, profitable, and debt-free, indicating a solid financial base. This positioning supports continued investment without reliance on external financing.
Strong Revenue Growth: Revenue is reported above $1 billion with indications of year-over-year increases into 2024 and sustained scale into FY2025, while cloud segments are noted as expanding strongly. These signals point to ongoing top-line momentum.
Market Expansion: Operations span 28 countries with 38 offices serving customers in 80+ countries, alongside recent moves such as a dedicated public-sector subsidiary and added international presence. This footprint suggests continued geographic and channel growth.
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in 2025 and accelerated further in early 2026, with adjusted operating income also rising. This points to broad-based top-line momentum beyond a single period.
Strong Market Position & Advantage: The company is characterized as the world’s largest asset manager with record-high assets under management and leading ETF scale. This scale advantage underpins continued client inflows and platform reach.
Diversified Revenue Streams: Growth is coming from multiple engines, including iShares ETFs, active strategies, private markets, and technology services such as Aladdin, alongside newer digital-asset offerings. This breadth reduces reliance on any single product line.



