

Top Tech Companies in Singapore (3,811)
Mondelēz International, Inc. (NASDAQ: MDLZ) is an American multinational confectionery, food, and beverage company based in Illinois which employs approximately 90,000 individuals around the world. Our Purpose Our purpose is to empower people to snack right. We will lead the future of snacking around the world by offering the right snack, for the right moment, made the right way. Our...
Mondelēz International's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be on an upward trajectory, with sales increasing in 2025 and continuing to rise into the second quarter of 2026. Company updates also indicate an improved full-year outlook, pointing to sustained top-line momentum.
Market Expansion: Geographic performance is described as broad-based, with emerging markets such as Latin America and AMEA cited as key contributors alongside gains in North America. Independent reporting notes that growth is supported across multiple regions rather than a single market alone.
Strong Market Position & Advantage: Category leadership in biscuits and a top-tier position in chocolate, supported by globally recognized brands, are portrayed as competitive advantages. This scale and brand portfolio underpin international distribution across more than 150 countries, aiding growth.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising steadily, including 11% year-over-year growth to $192.8 million in Q2 2026 and 7% growth for full-year 2025. The step-up from 6% growth in Q1 2026 to 11% in Q2 indicates accelerating momentum.
Profitability: Adjusted EBITDA increased 30% year over year in Q2 2026 as margin expanded from 34% to 37%, signaling operating leverage. Net income also improved to $19.4 million from $11.1 million year over year in that quarter.
Healthy Cash Flow: Guidance points to free-cash-flow growth in the high-40% range for 2026 alongside adjusted EBITDA growth of more than 20%. Operating cash flow reached $57.4 million in Q2 2026.

Bounteous is a global AI Services firm where agentic engineering and human experience converge to deliver transformative business outcomes for the enterprise. We help organizations design, build, and scale AI-driven products, platforms, and processes. With more than 5,000 team members worldwide, Bounteous delivers AI that sticks, powering adoption and outcomes that move organizations from experimentation to true transformation.

Bounteous's Top Stability & Growth Strengths
Market Expansion: Mergers and acquisitions have broadened global reach and scale, highlighted by the Accolite combination and the Cartesian acquisition adding specialists across North America and Europe. Active recruitment and an international footprint across the Americas, EMEA, and APAC reinforce an expanding operational presence.
Innovation-Driven Growth: A clear pivot toward enterprise AI, data analytics, and agentic engineering is emphasized through new capabilities and practices. Joining Anthropic’s Claude Partner Network underscores investment in AI-led services even if specific revenue impact is not disclosed.
Strategic Partnerships: High-profile ecosystem ties, including a launch Preferred Services Partner role with Anthropic and additional tech alliances such as Pendo, are positioned to enable enterprise-scale programs. These partnerships are presented as deepening credibility and opening growth pathways without quantifying near-term contribution.
MarketAxess is on a journey to digitally transform one of the world's largest financial markets, enabling the shift from analog, phone-based trading to a fully electronic marketplace. Why does this matter? Because our platform makes trading fixed-income more accessible, ultimately improving transparency, efficiency and competition in the marketplace. Changing the way an established industry transacts is no easy feat. There...

MarketAxess's Top Stability & Growth Strengths
Strong Market Position & Advantage: The company is widely regarded as a leading electronic platform in institutional fixed income, particularly in corporate credit, supported by substantial trading volumes and an extensive client network. Evidence includes strong momentum in portfolio and block trading alongside recognition within the competitive landscape.
Market Expansion: International and non-U.S. credit businesses are expanding, with revenue outside U.S. credit growing meaningfully in 2025 and again during 2026, and emerging-markets commissions increasing. This indicates continued broadening beyond the core U.S. credit market.
Diversified Revenue Streams: Services and data/technology revenues are rising, providing growth beyond transaction commissions. Examples include double-digit increases in information services and record services revenue in recent quarters.
Welcome to Comcast. From the connectivity and platforms we provide to the content and experiences we create, we bring people together, globally. Our people think the world of our work, and that’s why our work is the best in the world.

Comcast's Top Stability & Growth Strengths
Diversified Revenue Streams: Wireless lines expanded to roughly 10.6 million with notable net additions, Peacock generated $1.8 billion in Q3 2026, and business services connectivity grew, indicating multiple engines beyond traditional cable. This mix helps balance softness in the core residential broadband business.
Product Line Growth: Peacock delivered consecutive profitable quarters with rising paid subscribers, while studios and broader entertainment revenue increased year over year. Theme parks were a strong contributor in 2025 even as recent conditions turned softer.
Healthy Cash Flow: Free cash flow increased substantially in 2025 to $19.24 billion, enhancing financial flexibility. Quarterly free cash flow in 2026 remained robust at above $4 billion.
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...

Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding quickly across recent years and into 2026, with broad-based gains in betting and media and an increased full-year outlook. The acceleration predates the latest acquisition, indicating underlying momentum in the core business.
Innovation-Driven Growth: Media and advertising products powered by platforms like GeniusIQ and BetVision are gaining traction, contributing to rapid expansion in the media technology segment. Betting technology is also advancing through added services, contract renewals, and new customer wins.
Future-Ready Strategy: Management raised full-year guidance and outlined multi-year targets while extending into adjacent areas such as digital sports media and prediction markets. The Legend acquisition expands capabilities and audience reach that can support the next phase of scale.

SteelSeries is a global leader in gaming. We create hardware and software that enhances the gaming experience, improves performance, and leads to winning. Want proof? Esports pros have won more prize money using our gear than with any other brand. Our philosophy is that professional quality gear benefits every gamer, whether they're playing with friends, streaming their favorite titles, or...

SteelSeries's Top Stability & Growth Strengths
Strong Market Position & Advantage: Market-share gains, including reaching the number-one global gaming-headset position, indicate a defensible competitive edge despite a challenging accessories market.
Profitability: Gross margin improved year over year to 39.2% in Q2 2026 and the gaming division’s profit margin reached 15.0%, pointing to healthier unit economics.
Innovation-Driven Growth: New products such as the Arctis Nova Pro Omni are credited with driving headset share gains and contributing to the division’s return to organic growth.
InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Strong Hiring & Retention: Employee headcount is increasing over the 2023–2026 period, indicating ongoing hiring momentum. Feedback suggests workforce expansion is sustained even if the pace has moderated recently.
Market Expansion: A new Jakarta office was opened in 2026 to deepen engagement across Southeast Asia. Operations span dozens of offices in many countries, supporting customers in more than 80 countries.
Innovation-Driven Growth: New offerings such as the Data Studio AI Assistant and continued development of healthcare interoperability products point to active product investment. Feedback suggests AI and healthcare enhancements are a current strategic focus.
.png)
We’re the manufacturing partner of choice that helps a diverse customer base design and build products that improve the world. We love to hear your thoughts, comments and ideas so feel free to like, share and comment away. Any question or opinion is good to go as long as it is respectful and falls within the scope of this page. Derogatory...
Flex's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with FY2026 net sales up 8.1% year over year, Q1 FY2027 up 21%, and full‑year FY2027 guidance raised to imply roughly 24% growth at the midpoint. Growth is led by AI data centers, cloud infrastructure, and power systems, with the latest quarter outpacing the prior year.
Profitability: Operating performance is improving, as FY2026 GAAP operating income rose 17% and adjusted EPS increased 25%, with adjusted operating margin up to 6.3%. These results indicate a better mix and stronger conversion of revenue into operating earnings.
Healthy Cash Flow: Cash generation is solid, with free cash flow of $1.06B in FY2026, above $1B for the second consecutive year. This reinforces the company’s ability to fund operations while growth accelerates.

Headquartered in New York City, Take-Two Interactive Software, Inc. is a leading developer, publisher, and marketer of interactive entertainment for consumers around the globe. We develop and publish products principally through Rockstar Games, 2K, and Zynga. Our strategy is to create hit entertainment experiences, delivered on every platform relevant to our audience through a variety of sound business models. Our...
Take-Two Interactive Software's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue and net bookings rose materially in FY2026, and guidance points to a further step-up in FY2027. The company highlights a sizable year-over-year increase in revenue and a higher bookings outlook tied to its pipeline.
Diversified Revenue Streams: Recurring consumer spending makes up a large share of results and mobile contributes meaningfully alongside console and PC franchises. This mix across Rockstar, 2K, and Zynga supports ongoing monetization between major releases.
Future-Ready Strategy: A defined pipeline anchored by the scheduled Grand Theft Auto VI launch and reaffirmed FY2027 bookings guidance signals preparation for the next growth phase. Management’s outlook ties expected expansion to both the new release and continued performance from sports and mobile titles.
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Results indicate broad-based top-line momentum, with operating revenue and recurring revenue both rising strongly year over year. Organic growth is also highlighted, showing that expansion is not solely acquisition-driven.
Market Expansion: Customer numbers increased and international markets, including the U.S., showed accelerated traction. Management outlook points to continued expansion through further investment in key regions.
Healthy Cash Flow: Free cash flow increased alongside growth in adjusted EBITDA. This suggests the business is scaling while continuing to generate solid cash.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Operating and net income remained positive even as revenue softened in recent quarters. This indicates an earnings base that is holding up during a period of slower demand.
Healthy Cash Flow: Free cash flow stayed positive with meaningful generation quarter to quarter, and guidance points to continued cash production. Liquidity is reinforced by a sizable balance of cash, cash equivalents, and government securities.
Future-Ready Strategy: Management is concentrating investment on the Command Platform, detection and response, exposure management, and AI-enabled security operations. This refocus aims to position the portfolio for a return to growth once the transition progresses.
Skillsoft (NYSE: SKIL) is a global leader in AI-native skills management for the human + AI era. By unifying learning, real-time skills intelligence, and workforce insights, Skillsoft helps enterprises build their Skillforce™ — humans and AI working together to drive measurable business outcomes. Through personalized, interactive learning across leadership, technology, and compliance, Skillsoft enables organizations to close critical skill gaps...

Skillsoft's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins improved even as sales contracted, and full-year adjusted EBITDA guidance was maintained despite a reduced revenue outlook. This points to better earnings execution and cost discipline.
Innovation-Driven Growth: AI-enabled offerings such as CAISY, AI Coach, and LX Design Studio show rising adoption and engagement. These signs indicate momentum in AI-powered skills development within the enterprise base.
Future-Ready Strategy: The company is refocusing on an AI-native skills management platform and core enterprise learning following the sale of Global Knowledge. This sharper portfolio focus suggests a strategic shift toward higher-potential, software-led growth.
We solve for advertising campaign and creative complexities - both key elements to the time/money savings and performance that brands, agencies and businesses seek. Our unified platform combines media, creative, and intelligence, offering end-to-end workflows powered by AI across the open and closed web. With over 700 brands and advertisers, we've proven that dynamic and personalized creative makes advertising impactful. We...
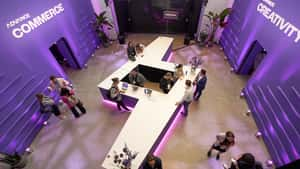
Smartly's Top Stability & Growth Strengths
Market Expansion: A new product, engineering, and commercial hub in Mexico City and operations across 25 countries with 17 regional offices indicate active geographic scaling. These investments suggest the company is building capacity to support North American and Latin American growth.
Product Line Growth: New AI-powered creative intelligence tools and the completed acquisition of INCRMNTAL expand capabilities into prediction, insights, and incrementality measurement. Added integrations across channels such as Reddit and CTV further broaden the platform’s scope.
Strong Market Position & Advantage: The company reports serving 800+ brands and an increase in managed ad spend from more than $6 billion to over $7 billion, signaling sustained platform relevance. Recognition as a leader in creative advertising technologies supports a credible competitive position.

Hudson River Trading brings a scientific approach to trading financial products. We have built one of the world's most sophisticated computing environments for research and development. Our researchers are at the forefront of innovation in the world of algorithmic trading.
Hudson River Trading's Top Stability & Growth Strengths
Strong Revenue Growth: Reported net trading revenue rose from roughly $8B in 2024 to about $12.3B in 2025, with additional momentum shown by multi-billion-dollar quarters in 2026. This trajectory points to a substantial scaling of trading activity and market presence.
Profitability: First-quarter 2026 reportedly delivered $4.2B in net profit alongside $6.4B in trading revenue, with subsequent reporting indicating another exceptionally strong quarter. Such earnings power suggests an ability to convert trading gains into significant bottom-line results.
Innovation-Driven Growth: The company is scaling AI and compute capacity through a multiyear, multibillion-dollar CoreWeave partnership and wider Nvidia-based infrastructure investments. This build-out underpins broader quantitative research and supports newer, longer-horizon strategies.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Healthy Cash Flow: Cash generation is described as substantial, with unlevered free cash flow of about $1.016B in 2025 and $283.5M in Q2 2026, indicating strong cash-producing ability despite modest top-line growth.
Profitability: Margins are portrayed as strong, with a 40.6% non-GAAP operating margin in 2025 and near 40% in Q2 2026, reflecting disciplined cost management and efficient operations.
Resilient & Sustainable Growth: Feedback suggests core revenue excluding FormSwift has returned to slight year-over-year growth and paying users have increased for several consecutive quarters, pointing to stabilization and incremental expansion.
.png)
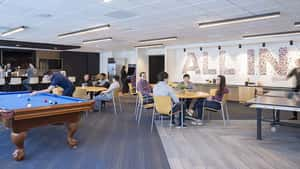
In March of 2002, Belvedere Trading emerged as Chicago’s newest market maker, soon to join the ranks of the Windy City’s elite proprietary trading firms. Armed with printouts of Excel workbooks and a team of eager minds, Belvedere established their place in the SPX pit on the floor of the Chicago Board Options Exchange. From the beginning, we have iteratively...
Belvedere Trading's Top Stability & Growth Strengths
Product Line Growth: Evidence indicates the firm expanded its product count in 2024, supporting a broader set of traded instruments. Company communications also point to continued development across additional products and marketplaces.
Future-Ready Strategy: Technology investment was stepped up in 2024, with materially increased computing resources and network capacity in a key data center. Ongoing emphasis on proprietary models, software, and infrastructure suggests preparation for scalable trading activity.
Market Expansion: The operating footprint spans Chicago, Boulder, New York, and Singapore, providing geographic reach and talent access. Independent documentation also describes a prior expansion of the Chicago office to accommodate a growing workforce.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 8% in 2025 and accelerated to 14% year over year in Q2 2026, with management raising full‑year revenue guidance to $16.05–$16.22 billion. Gross bookings also rose 8% in 2025 and 12% in Q2 2026, indicating expanding underlying travel activity.
Profitability: Operating income grew 42% in 2025 and surged 65% in Q2 2026, while GAAP net income jumped 166% in that quarter. Adjusted EBITDA rose 19% in 2025 and 23% in Q2 2026, suggesting improved operating leverage alongside growth.
Diversified Revenue Streams: Both distribution channels are contributing, with Q2 2026 B2B gross bookings up 21% (B2B revenue up 23%) and B2C gross bookings up 8%. Lodging remained a key driver as lodging gross bookings rose 11% and booked room nights increased 6% in Q2 2026.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding strongly over multiple years, with recent quarters delivering double-digit increases and an upgraded full‑year outlook. Underlying demand also appears robust as gross booking volume and new signed enterprise bookings have risen sharply.
Market Expansion: The customer base has grown to more than 12,500 with record new signed enterprise bookings and expansion into regions such as Europe and India. Added offerings like meetings and events further broaden the company’s reach across segments and geographies.
Healthy Cash Flow: Operating cash flow and free cash flow turned positive for the latest full fiscal year, and the company reported positive cash generation in a recent quarter. This suggests improving operating leverage even as the business scales.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analyst recognitions across 2024–2025, including Leader placements in application security testing and SAST, indicate Snyk competes at the top of its market. This standing supports commercial durability even as overall growth moderates.
Product Line Growth: Snyk Code surpassed $100M in ARR in 2024 and the DAST business recorded 245% quarter-over-quarter ARR growth after the Probely acquisition, broadening revenue contributors. Expansion across code, open source, containers, IaC, APIs, and AI security points to a wider product footprint.
Innovation-Driven Growth: Investments in AI security—such as Evo and the acquisition of Invariant Labs—reflect an active innovation agenda targeting emerging developer and AI risks. These moves are positioned as potential growth engines alongside the core platform.



