

Top Software Companies in Singapore (1,060)
We solve for advertising campaign and creative complexities - both key elements to the time/money savings and performance that brands, agencies and businesses seek. Our unified platform combines media, creative, and intelligence, offering end-to-end workflows powered by AI across the open and closed web. With over 700 brands and advertisers, we've proven that dynamic and personalized creative makes advertising impactful. We...
Smartly's Top Stability & Growth Strengths
Market Expansion: A new Product, Engineering and Commercial Hub in Mexico City was opened in March 2026, with operations reported across 25 countries and 17 regional offices. Customer and platform scale advanced to 800+ brands and $7B+ in managed ad spend by 2026.
Product Line Growth: Capabilities expanded beyond social advertising into audio and CTV via integrations such as Spotify and Roku, and into measurement through the INCRMNTAL acquisition. Additional channel integrations like LinkedIn further broaden the platform’s addressable market.
Strong Market Position & Advantage: Recognition as a Leader in The Forrester Wave: Creative Advertising Technologies (Q4 2024) alongside multi‑billion‑dollar ad‑spend scale across hundreds of brands points to a defensible position. Broad partnerships across major advertising platforms reinforce this standing.
Skillsoft (NYSE: SKIL) is a global leader in AI-native skills management for the human + AI era. By unifying learning, real-time skills intelligence, and workforce insights, Skillsoft helps enterprises build their Skillforce™ — humans and AI working together to drive measurable business outcomes. Through personalized, interactive learning across leadership, technology, and compliance, Skillsoft enables organizations to close critical skill gaps...

Skillsoft's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted EBITDA held roughly stable to slightly higher year over year and free cash flow improved in the latest periods, indicating tighter operations despite softer sales. Management focus on efficiency helped margins while the business pivots toward subscriptions and AI.
Innovation-Driven Growth: A next‑generation AI‑native Percipio platform is in market with new customers, and usage of AI capabilities (including CAISY and related tools) is rising among early adopters. These signals point to product‑led momentum within the core enterprise offering even as consolidated revenue declines.
Customer Loyalty & Retention: Enterprise subscription revenue has been comparatively resilient across recent years, with indicators like improved dollar retention and steady TDS performance suggesting stable customer relationships. Professional‑services revenue also increased, reinforcing ongoing engagement with enterprise accounts.
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.
Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased solidly year over year in both the latest quarter and the full fiscal year, with momentum characterized as robust and consistent across recent periods. Company materials indicate the expansion is driven by contributions from both existing and newly added customers.
Healthy Cash Flow: Free cash flow turned positive and rose meaningfully, alongside improvements in non-GAAP operating income. These trends indicate improving cash profitability even as GAAP profitability has yet to be reached.
Customer Loyalty & Retention: Net retention indicates expansion within existing accounts, and the cohort of larger enterprise customers has grown. Together, these signals point to durable upsell and cross-sell within the installed base.
At monday.com, we help teams get more work done. We are the best AI work platform that empowers teams to automate, build, and scale their impact end-to-end with tools that actually execute the work for you. With over $1B in ARR, 250,000+ customers, and a global team, we’re serious about building a product people love to use and giving our...

monday.com's Top Stability & Growth Strengths
Profitability: Net income reached $118.7 million in 2025 versus $32.4 million in 2024 and a small loss in 2023, alongside record non‑GAAP operating income and margin improvements in 2026. This indicates the company is scaling efficiency while expanding.
Strong Revenue Growth: Revenue rose 27% in 2025 to $1.232 billion and continued to increase 22% year over year in Q2 2026, with management guiding 19%–20% growth for 2026. While the pace has moderated from earlier years, the top line remains firmly upward.
Innovation-Driven Growth: ARR from AI products doubled quarter over quarter in Q2 2026 and represented 17% of net new ARR. The pivot to an AI work platform is contributing discernible incremental demand.
.png)
In March of 2002, Belvedere Trading emerged as Chicago’s newest market maker, soon to join the ranks of the Windy City’s elite proprietary trading firms. Armed with printouts of Excel workbooks and a team of eager minds, Belvedere established their place in the SPX pit on the floor of the Chicago Board Options Exchange. From the beginning, we have iteratively...
Belvedere Trading's Top Stability & Growth Strengths
Product Line Growth: Company updates point to a meaningful increase in product count in 2024, expanding the breadth of tradable products. Available evidence suggests this reflects operating-scale growth beyond hiring alone.
Market Expansion: The firm operates across Chicago, Boulder, New York, and Singapore, and signals expansion into new instruments and marketplaces domestically and globally. Physical office build-outs in Chicago further indicate an expanded footprint to accommodate growth.
Innovation-Driven Growth: Reported large increases in computing resources and major network upgrades in 2024 underscore ongoing investment in proprietary technology and infrastructure. Available evidence suggests these capacity gains are aimed at scaling trading capabilities.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.
Headquartered in New York City, Take-Two Interactive Software, Inc. is a leading developer, publisher, and marketer of interactive entertainment for consumers around the globe. We develop and publish products principally through Rockstar Games, 2K, and Zynga. Our strategy is to create hit entertainment experiences, delivered on every platform relevant to our audience through a variety of sound business models. Our...
Take-Two Interactive Software's Top Stability & Growth Strengths
Strong Revenue Growth: FY2026 net revenue and Net Bookings increased meaningfully year over year, showing robust top-line momentum. Growth was evident across multiple quarters rather than being confined to a single period.
Customer Loyalty & Retention: Recurrent consumer spending expanded and made up the majority of total Net Bookings, indicating durable engagement across key franchises. This ongoing spend supports steadier performance between major releases.
Future-Ready Strategy: Outlook points to a step-up in FY2027 Net Bookings, anchored by the upcoming Grand Theft Auto VI launch and a broader release pipeline. During FY2026, expectations were raised as results outpaced earlier assumptions, reinforcing a forward-leaning posture.
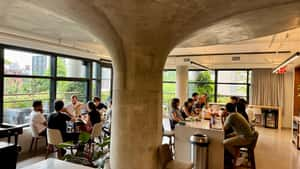
Genius Sports is the layer between what happens on the field and how the world engages with it. Our solutions across the global sports ecosystem are underpinned by our next generation big data and artificial intelligence platform, GeniusIQ. By ingesting and computing multiple real-time data feeds, GeniusIQ powers a wide range of functions and applications across sports performance and officiation, fan engagement,...
Genius Sports's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show consistent top-line increases through 2025 and into 2026, including a sharp acceleration in Q2 2026. Guidance was raised above $1B for 2026, underscoring momentum.
Strategic Partnerships: Long-term, often exclusive relationships with tier‑one rights holders such as the NFL (through 2029), Football DataCo/Premier League (through 2029) and the NCAA (through 2032) reinforce commercial visibility. These agreements expand distribution and underpin growth across betting and media.
Innovation-Driven Growth: Product advances like GeniusIQ, BetVision, and Second Spectrum tracking are cited as drivers of expanding media and betting solutions. This innovation push aligns with rapid Media segment growth and broader market expansion.

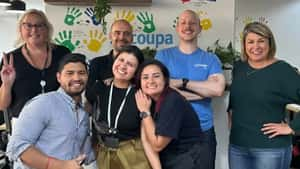
Coupa is a global technology company that helps businesses run smarter by connecting all the ways they spend money — from procurement and expenses to payments and supply chain decisions — in one intelligent platform. In simple terms, Coupa gives organizations the visibility and control they need to make better financial choices, reduce waste, and drive real impact. It’s where...
Coupa's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as reaching a record level in Q4 FY2026, with continued ARR growth and earlier double‑digit bookings gains indicating ongoing top‑line momentum.
Customer Loyalty & Retention: Renewals and expansions are emphasized, with more than 1,300 organizations renewing or expanding in FY2026. This points to durable engagement within the installed base.
Innovation-Driven Growth: Product advances such as AI agents and new applications, alongside acquisitions like Rossum and Tonkean, are expanding the platform’s capabilities. These moves are linked to increased adoption and expansion activity.

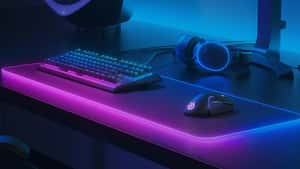
SteelSeries is a global leader in gaming. We create hardware and software that enhances the gaming experience, improves performance, and leads to winning. Want proof? Esports pros have won more prize money using our gear than with any other brand. Our philosophy is that professional quality gear benefits every gamer, whether they're playing with friends, streaming their favorite titles, or...
SteelSeries's Top Stability & Growth Strengths
Strong Revenue Growth: Long-term results show meaningful revenue expansion, including strong increases through 2024 and a return to organic growth in 2026. Management also outlined expectations for further growth in 2026, following a record quarter at the end of 2024.
Strong Market Position & Advantage: The business consistently gained market share even during a softer 2025, and corporate materials described an improved market‑leading position in core gaming gear. This outperformance versus a weak category underscores a durable competitive footing.
Innovation-Driven Growth: New product rollouts and a steady launch cadence—such as recent premium headset introductions—are driving momentum and stronger mix. Product‑cycle tailwinds supported late‑2024 strength and the 2026 recovery.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Consolidated revenue has increased across recent years, with additional year-over-year gains extending into early 2026. This pattern indicates ongoing top-line expansion even as quarterly and annual growth rates vary.
Profitability: Operating income reached new highs in 2025 and continued to rise in subsequent quarters. This points to improving operating leverage alongside revenue growth.
Product Line Growth: Businesses such as Morningstar Credit, PitchBook, Retirement, and the Direct Platform are cited as key growth engines, with Credit standing out. This breadth of product contributions supports expansion beyond a single offering.
Citadel Securities is a technology-driven, next-generation global market maker. We provide institutional and retail investors with world-class liquidity, competitive pricing and seamless front-to-back execution in a broad array of financial products. Our teams of engineers, traders and researchers harness leading-edge quantitative research and the accelerating power of compute, machine learning and AI to power our analytics and tackle the market’s...
Citadel Securities's Top Stability & Growth Strengths
Strong Revenue Growth: Reported 2025 trading revenue rose to $12.2B from $9.7B in 2024, and 2026 featured record quarters such as a $7.3B Q2, indicating material topline expansion. EBITDA was also reported higher in 2025, reinforcing financial momentum.
Strong Market Position & Advantage: The company indicates it executes a substantial portion of daily U.S. equity and retail trading volumes and holds a top rank on Tradeweb for U.S. Treasury flows, underscoring entrenched scale. Leadership in listed options and as an NYSE Designated Market Maker further points to durable competitive advantage.
Market Expansion: New initiatives such as launching a High Touch Equities business in late 2025, opening an Amsterdam office in 2026, and operating across 50+ equity and fixed‑income markets signal active expansion. Ongoing hiring—1,800+ employees, dozens of open roles across regions, and the firm’s largest intern class—suggests continued investment in capacity.

Hilton (NYSE: HLT) is a leading global hospitality company with a portfolio of 22 world-class brands comprising nearly 7,300 properties and more than 1.1 million rooms, in 123 countries and territories. Dedicated to fulfilling its founding vision to fill the earth with the light and warmth of hospitality, Hilton has welcomed more than 3 billion guests in its more than...
Hilton's Top Stability & Growth Strengths
Market Expansion: Hotel footprint is widening, with properties and rooms increasing, approvals for additional rooms, and a record development pipeline by mid-2026. The network spans over 140 countries and reflects continued entry into new markets.
Strong Revenue Growth: Revenue rose to about $12.04B in 2025 from the prior year, and early 2026 showed gains in system-wide comparable RevPAR. Management also indicated continued comparable RevPAR growth for 2026.
Product Line Growth: The portfolio is expanding with new brands and lodging categories, including the Apartment Collection and the conversion-focused Outset Collection. Broader offerings in lifestyle and luxury support conversions and attract a wider range of owners and travelers.
Qualtrics is trusted by thousands of the world’s best organizations to power exceptional customer and employee experiences that build deep human connections, increase customer loyalty, boost employee engagement, and drive business success. Our advanced AI and specialized Experience Agents™ allow businesses and governments to proactively interact with customers and employees in personalized ways across every channel and touchpoint, respond in-the-moment...
Qualtrics's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue appears to be increasing over time, with evidence of substantial growth in 2022 and continued year-over-year expansion into early 2023, even as the pace moderates. Feedback suggests the business is still scaling toward a larger revenue base while transitioning to a mature growth profile.
Profitability: Independent credit commentary highlights improved profitability and a deliberate shift toward a profit-focused operating model. Feedback suggests efficiency gains and margin improvement are becoming central to the company’s stability and growth trajectory.
Innovation-Driven Growth: Ongoing AI platform investment, rising adoption of AI capabilities, and product expansion including acquisitions are cited as current growth engines. Feedback suggests these initiatives are supporting continued operational and market expansion.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
CSC is a global leader in providing business, legal, tax, and digital brand services to companies around the world. With more than 8,000 employees, CSC operates in more than 140 jurisdictions, delivering solutions that help businesses thrive. We pride ourselves on our client-focused approach, market-leading expertise, and unmatched global reach.
CSC's Top Stability & Growth Strengths
Strong Market Position & Advantage: Customer base is described as including a very large share of major global enterprises across Fortune-ranked companies, top brands, and leading private equity firms, indicating entrenched enterprise reach. This positioning underscores a strong competitive footing across multiple service lines.
Market Expansion: Operations have scaled to capabilities in more than 140 jurisdictions, aided by the approximately $3 billion Intertrust acquisition and its full integration in 2024. Continued investment and activity are highlighted across Europe, the Americas, Asia-Pacific, and the Middle East.
Product Line Growth: The company has expanded from incorporation services into corporate/legal compliance, fund administration, capital markets, tax, digital brand protection, domain services, and global subsidiary management. Corporate and Legal Solutions is described as the largest revenue-generating unit with a sizable workforce.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.



